As a former Wall Street executive and licensed Certified Financial Planner (CFP), I have seen firsthand how lenders actively engineer products to keep you trapped in a perpetual cycle of interest. The economic headwinds of 2026 have pushed average credit card interest rates dangerously close to 20%, with subprime borrowers suffering under punitive rates exceeding 29.99%. To survive this environment and break the cycle, identifying the best debt relief programs 2026 has available is the most critical step toward protecting your wealth and reclaiming your financial independence.
Banks rely on your minimum payments to pad their quarterly earnings while your principal balance barely moves. If you are reading this, you are likely feeling the crushing weight of high-interest revolving debt, but you are absolutely not out of options.
This guide strips away the banking industry’s smoke and mirrors to reveal the most effective strategies for breaking free. I will walk you through the top 5 debt relief programs available to US consumers this year, breaking down the exact underwriting metrics, legal loopholes, and financial mechanics you need to take back your wealth.
It is time to stop playing by the lenders’ rules and start using their own institutional frameworks against them.
Quick Financial Specs (At a Glance)
Before you commit to a strategy, you must understand exactly how it impacts your credit profile, your cash flow, and your legal liability. Every debt relief program carries unique risks, and choosing the wrong vehicle can trigger aggressive collection actions or massive tax penalties.
Below is my proprietary comparison matrix, built from current 2026 lending benchmarks.
| Lender/Strategy Option | Benchmark APR Range | Minimum FICO Required | Hidden Fees/Origination Costs | Best For |
| 0% Balance Transfer Card | 0% for 12-21 months | 690+ (Good to Excellent) | 3% to 5% transfer fee upfront | High earners needing a brief window to aggressively kill principal. |
| Debt Consolidation Loan | 7.99% – 24.99% | 640+ | 1% to 8% origination fee | Borrowers with decent credit wanting a fixed 36-to-60 month payoff. |
| NFCC Debt Management Plan | Reduced to 6% – 10% | None (No credit check) | $30 – $50 monthly maintenance fee | Consumers overwhelmed by high APRs but capable of steady monthly payments. |
| For-Profit Debt Settlement | N/A (Accounts default) | None (Scores will drop) | 15% to 25% of enrolled debt | Borrowers nearing bankruptcy who cannot afford their current minimums. |
| Chapter 7 Bankruptcy | N/A (Debt discharged) | None (Requires Means Test) | $1,500 – $3,000 attorney/filing fees | Severe insolvency where liabilities massively outpace liquid assets. |
The Debt Trap vs. Strategic Consolidation
Lenders call revolving credit card debt “sticky money” because it is designed to be mathematically impossible to escape if you only pay the minimums. Let’s strip away the marketing and look at the brutal, unvarnished mathematics of the debt trap.
Assume you are holding a $10,000 balance on a standard rewards credit card carrying a 24% APR. If you aggressively try to pay this off over a standard 36-month window, your monthly payment is roughly $392.
By the time you make that final payment, you will have handed the bank $4,123 in pure, unamortized interest. That is a 41% premium on your original purchases just for the privilege of carrying a balance.
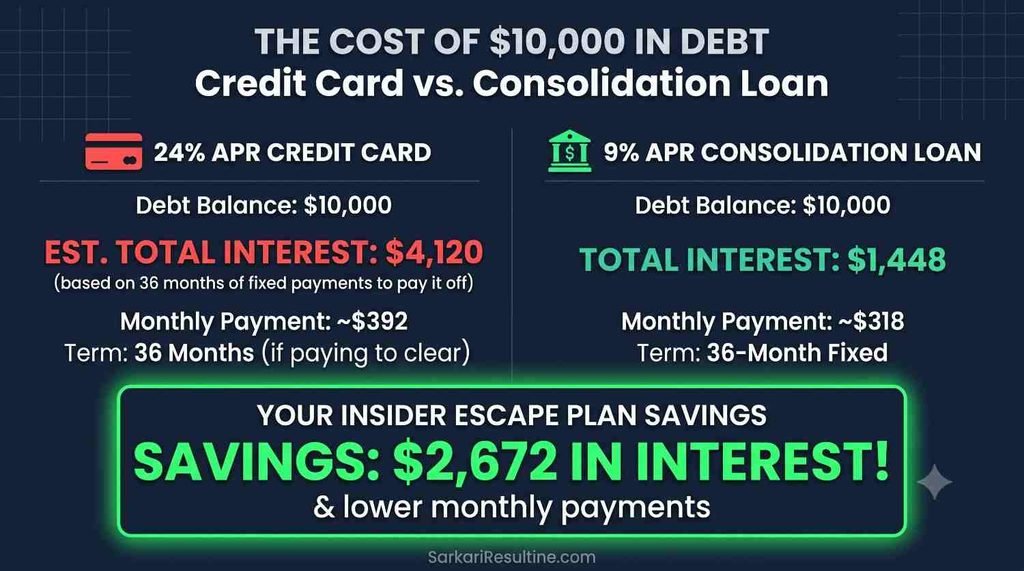
Now, let’s contrast that with a structured debt consolidation loan. If you secure a $10,000 personal loan at a 9% APR for that same 36-month term, your monthly payment drops to $318.
More importantly, your total interest paid plummets to just $1,448. By simply swapping the financial vehicle and locking in a fixed rate, you instantly rescue $2,675 of your own wealth from the bank’s profit margins.
Federal Consumer Protections & Fine-Print Pitfalls
You are not fighting the banks alone; the US government has established powerful statutory frameworks to shield you from predatory practices. The Truth in Lending Act (TILA) requires lenders to clearly disclose your total finance charges, exact APR, and payment schedule before you sign anything. If a lender attempts to hide these numbers, they are in direct violation of federal law.
However, the fine print is where lenders bury their traps, specifically through prepayment penalty clauses. Always verify that your consolidation loan explicitly states there is no penalty for paying off the principal early.
If you opt for a debt settlement program, you are governed by the Federal Trade Commission (FTC) rules. The FTC mandates that for-profit settlement companies cannot charge you upfront fees before they successfully negotiate a reduction in your debt. If a settlement firm asks for a retainer before doing the work, walk away immediately.
Furthermore, be hyper-aware of the tax implications surrounding canceled debt. Under IRS regulations, any forgiven debt over $600 is reported on a Form 1099-C and treated as taxable income. Unless you can prove legal insolvency, the IRS expects you to pay income tax on the amount the bank wrote off.
Required Verification & Documentation Checklist
Underwriting standards have tightened significantly in 2026, meaning you must build an airtight financial dossier before requesting rate reductions or consolidation loans. Lenders are terrified of default risk, so you must proactively prove your liquidity and stability. Walking into an application blindly is a guaranteed way to trigger a hard inquiry and a subsequent denial.
Gather the following documents and keep them in a secure digital folder:
- Proof of Income: Your two most recent consecutive pay stubs, last year’s W-2 forms, or your 1099s and Schedule C if you are an independent contractor.
- Liability Inventory: The latest billing statements for every targeted credit card, specifically noting the current balance, exact APR, and the account number.
- Asset Verification: Two months of consecutive bank statements (checking and savings) to prove you have the cash reserves to handle the new loan’s origination fees and first payment.
- Identity Validation: A valid, unexpired state-issued ID or US Passport, alongside a recent utility bill to verify your physical residential address.
Copy-Paste Legal Financial Draft (Dispute / Hardship / Negotiation Letter)
Sometimes, the most profitable move is calling your lender directly to negotiate a lower APR or a temporary hardship forbearance. Banks do not want you to default; they would rather accept a reduced profit margin than sell your account to a junk debt buyer for pennies on the dollar.
Use this exact, legally sound template to bypass low-level customer service reps and trigger an internal risk review. Send this via Certified Mail or read it verbatim to a retention supervisor.
[Your Name]
[Your Physical Address]
[Your Phone Number]
[Your Email Address]

[Date]

[Lender/Bank Name]
Attn: Executive Escalations / Hardship Department
[Bank Address from your statement]

RE: Request for APR Reduction & Hardship Forbearance Review
Account Number: [Your Account Number]
Certified Mail Tracking Number: [Insert Tracking Number]

Dear Servicing Manager,

I am writing to formally request a temporary hardship forbearance and a permanent reduction of the Annual Percentage Rate (APR) on the above-referenced account. I have been a loyal customer since [Year Account Opened], consistently maintaining a strong payment history.

Due to a recent, unforeseen change in my macroeconomic circumstances [Optional: briefly mention job transition, medical emergency, or unexpected mandatory expenses], my current minimum payment at the revolving rate of [Current APR]% has become mathematically unsustainable. I am proactively contacting you to prevent this account from falling into delinquency.

Under current internal retention guidelines and general consumer forbearance protocols, I am requesting that my APR be reduced to a fixed rate below 10%, or that my account be placed on a 6-month hardship program with waived penalty fees. I prefer to resolve this directly with [Lender Name] rather than transferring this balance to a competitor's 0% promotional offer or enrolling the account in an NFCC Debt Management Plan.

Please contact me within ten (10) business days to confirm the restructured terms of this account. If I do not hear from your executive team, I will be forced to execute alternative debt relief measures that will close this trade line permanently.

Sincerely,

[Your Signature]
[Your Printed Name]
Step-by-Step Application & Underwriting Blueprint
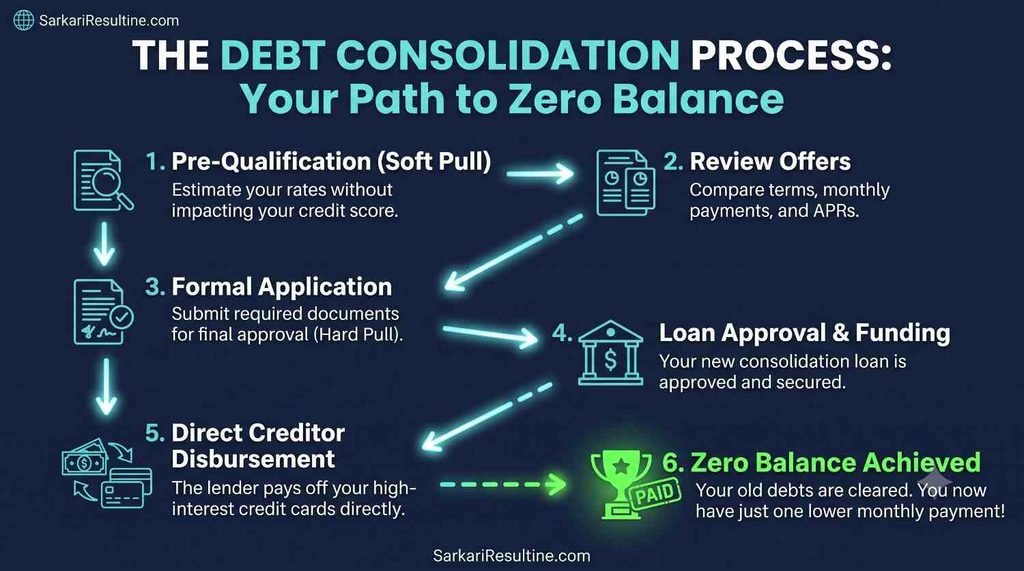
If you decide that a debt consolidation loan is your best path forward, you must treat the application process like a military operation. Do not blindly apply for the first offer you receive in the mail. Every hard pull on your credit report drops your FICO score by 3 to 5 points, which can shift you into a higher interest rate tier.
Follow this exact sequential roadmap to secure funding:
- The Soft Pull Reconnaissance: Use aggregation platforms like Bankrate or NerdWallet to pre-qualify for multiple loans using a “soft pull,” which does not harm your credit.
- The FICO Triage: Pull your official reports from annualcreditreport.com to ensure there are no erroneous collections dragging down your score before you officially apply.
- The Rate Lock: Select the lender offering the lowest combined APR and origination fee, ensuring the monthly payment comfortably fits below 36% of your gross debt-to-income (DTI) ratio.
- The Direct Disbursement Demand: Whenever possible, instruct the new lender to disburse the funds directly to your credit card issuers. This proves to the underwriter that you are actively retiring debt, not just taking cash to spend.
- The Account Freeze: Once the credit cards hit a zero balance, physically freeze them or cut them up. Do not close the accounts, as closing them destroys your credit utilization ratio and damages your credit age.
Predatory Loan Traps: Red Flags to Identify
The debt relief industry is unfortunately swimming with predatory bad actors looking to capitalize on your financial desperation. One of the biggest traps in 2026 is the “guaranteed approval” tribal payday loan. Because these lenders operate under sovereign tribal immunity, they frequently bypass state usury laws, legally trapping borrowers in loans with APRs exceeding 300%.
Another massive red flag is the “bait-and-switch” origination fee. Predatory lenders will advertise a highly attractive 8.99% APR, but bury a devastating 8% to 10% origination fee deep in the TILA disclosures. If you borrow $20,000, they instantly skim $2,000 off the top, leaving you with only $18,000 to pay off your debts while charging you interest on the full twenty.
Finally, be incredibly wary of aggressive debt settlement pitches promising to “wipe out your debt for pennies on the dollar.” These companies instruct you to intentionally default on your cards, devastating your credit score by over 100 points. They fail to warn you that your creditors can—and often will—sue you for breach of contract before a settlement is ever reached.
An Insider CFP’s Strategic Wealth Accelerators
Once you have stopped the bleeding and stabilized your high-interest debt, it is time to pivot from defense to offense. Standard financial advice tells you to just keep paying your bills on time. Elite wealth management requires you to actively manipulate the credit system to accelerate your net worth.
For more insider strategies on managing your wealth and protecting your legal rights, explore the complete guides at SarkariResultine.com. In the meantime, deploy these advanced tactics:
The Balance Transfer Fee Neutralizer
If you utilize a 0% APR balance transfer card, you will typically be hit with a 3% to 5% transfer fee. To neutralize this, take the exact dollar amount of the fee and immediately slash it from your discretionary monthly budget (e.g., dining out, subscriptions) over the first three months. You essentially “refund” yourself the banking fee, ensuring you get true 0% financing without losing a dime of your actual net worth.
Strategic Authorized User Tradelines
If your credit score was damaged during your debt struggle, you can artificially inflate it by “piggybacking.” Have a highly responsible family member add you as an authorized user to their oldest, flawless credit card with a high limit and zero balance. The entire positive history of that trade line instantly imports to your credit profile, drastically lowering your overall credit utilization ceiling and rapidly boosting your FICO score.
The Rapid Debt Avalanche Switch
Many consumers use the “Debt Snowball” method (paying small balances first for a psychological win). As a CFP, I demand my clients use the “Debt Avalanche.” You must ruthlessly target the debt with the absolute highest mathematical APR first, regardless of the balance size. The math is undeniable: the Avalanche method guarantees you pay the least amount of total interest and achieve debt freedom months faster than any other strategy.
Essential US Regulatory & Financial Portals
Do not rely on third-party blogs or TikTok influencers for legal financial boundaries. Bookmark these official institutional portals to verify your rights, report predatory behavior, and pull your statutory data.
- Consumer Financial Protection Bureau (CFPB) – consumerfinance.gov: Use this portal to file an aggressive, legally-binding complaint against lenders who refuse to honor terms, hide fees, or fail to process your payments correctly.
- Federal Trade Commission (FTC) – ftc.gov: The ultimate authority on debt collection laws; use their resources to understand your rights under the Fair Debt Collection Practices Act (FDCPA) and report abusive debt settlement scams.
- Internal Revenue Service (IRS) – irs.gov: Essential for reviewing the exact tax liabilities regarding Form 1099-C (Cancellation of Debt) and determining if you qualify for the insolvency exclusion.
- Annual Credit Report – annualcreditreport.com: The only federally authorized website where you can pull your complete, unredacted credit files from Equifax, Experian, and TransUnion for free without hidden subscription traps.
Top 5 Frequently Asked Questions
1. Will enrolling in a debt relief program ruin my FICO score?
It depends entirely on the program you choose. A debt consolidation loan or a 0% balance transfer will initially drop your score by a few points due to the hard inquiry, but your score will quickly surge as your credit utilization ratio plummets. Conversely, debt settlement requires you to intentionally default, which will crash your FICO score by well over 100 points and leave derogatory marks for seven years.
2. What is a “good” debt consolidation APR in 2026?
With the Federal Reserve’s current rate environment, a “prime” borrower (FICO 720+) should demand an APR between 7.99% and 11.99%. If your FICO is in the mid-600s, expect rates between 14% and 18%. Anything over 24% is predatory, and you are better off calling your current creditors to negotiate a hardship plan. For more insider strategies on managing your wealth and protecting your legal rights, explore the complete guides at SarkariResultine.com.
3. Do I have to pay taxes on debt that is forgiven through settlement?
Yes, under current IRS guidelines, any canceled debt exceeding $600 is considered taxable income. You will receive a Form 1099-C at the end of the year, and you must report it. The only legal loophole is filing IRS Form 982 to prove you were financially “insolvent” (your total liabilities exceeded your total assets) at the exact time the debt was canceled.
4. How does a Credit Counseling Debt Management Plan (DMP) actually work?
When you enroll with a non-profit NFCC-certified agency, they negotiate directly with your creditors to slash your punitive interest rates—often dropping a 29% APR down to 6% or 10%. You make one single monthly payment to the agency, and they disburse the funds to the banks. You will be required to close your active credit cards, which temporarily dings your credit score, but it guarantees you are entirely debt-free in 3 to 5 years.
5. Can my bank sue me if I stop paying my credit cards?
Absolutely, and in 2026, lenders are more litigious than ever. If you simply stop paying your minimums to attempt debt settlement, the creditor has the legal right to file a lawsuit for breach of contract. If they win a default judgment, they can legally garnish your wages, seize funds directly from your checking account, or place a lien on your property. Never default on a debt without understanding the severe legal consequences.