
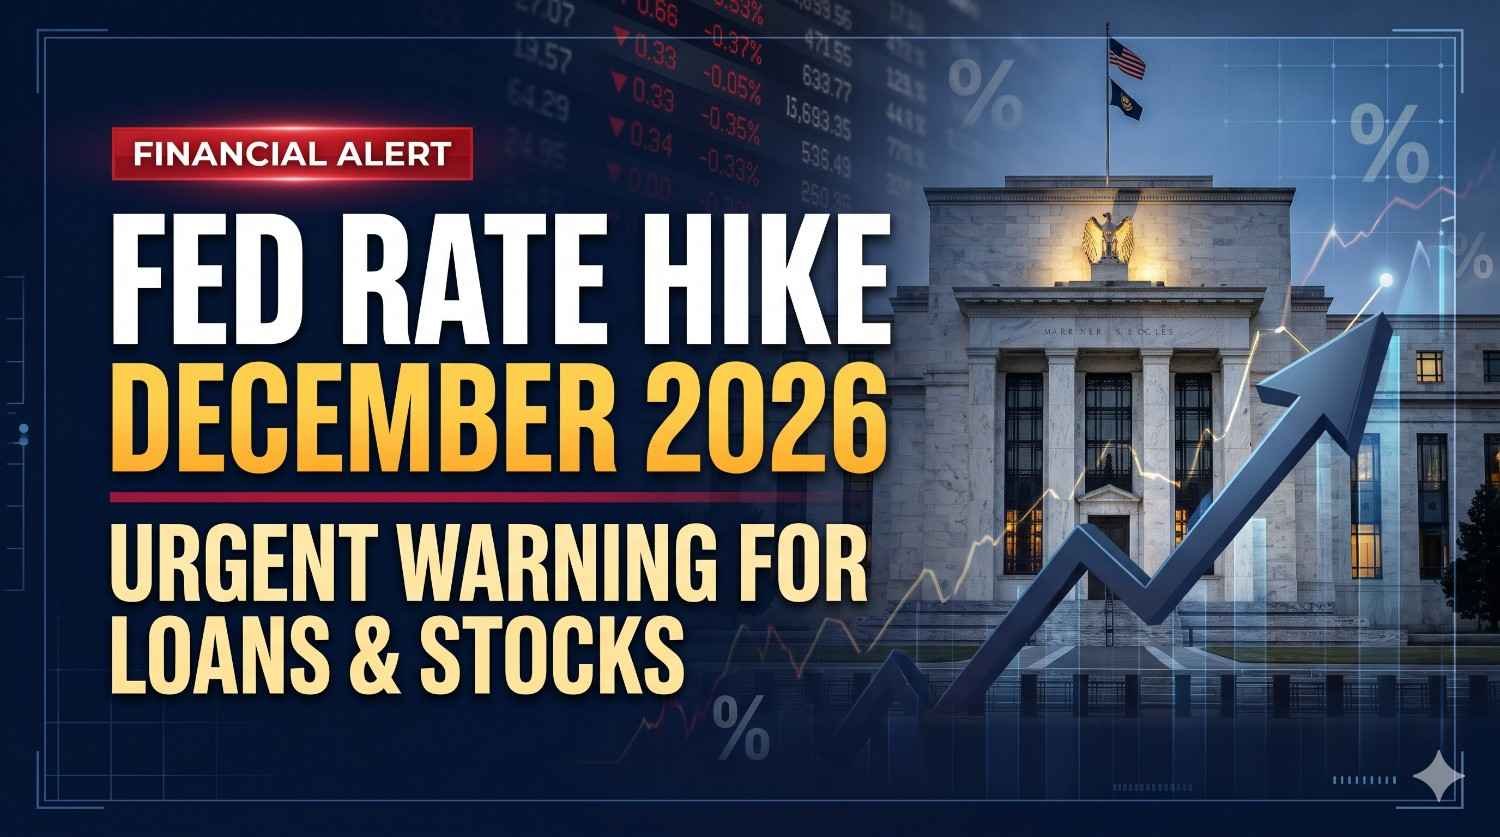
WASHINGTON — American borrowers and Wall Street investors face a high-stakes Fed rate hike December 2026 showdown after two senior Federal Reserve governors warned that sticky inflation demands steeper borrowing costs. Markets now price an 86% to 97% chance of tightening when the Federal Open Market Committee concludes its December 8–9 policy meeting.
With the benchmark federal funds rate sitting at 3.75% to 4.00%, Governor Christopher Waller floated an aggressive half-point increase unless policymakers clearly commit to another January move. Meanwhile, Governor Lisa Cook defended her rare October dissent on November 20, 2026, warning that waiting risks letting inflation become permanently entrenched.
Key Takeaways (Fast Facts):
- Who: Federal Reserve Governors Christopher Waller, Lisa Cook, and the 12-member FOMC under Chair Kevin Warsh.
- What: High probability of a 25-basis-point rate hike, with 50 basis points actively debated.
- When: Decision drops December 9, 2026, at 2:00 p.m. EST.
- Where: Washington, D.C., impacting US mortgages, credit cards, auto loans, and equities nationwide.
- Why: Stubborn 0.3% monthly core CPI, AI capital spending, and oil shocks.
- Key Metric: 30-year mortgage rates hit 7.28% as 10-year Treasury yields brushed 5.05%.
Fed Rate Hike December 2026: What Triggered the Official Shift
The path toward a Fed rate hike December 2026 accelerated after the central bank released the FOMC October 27–28, 2026 Meeting Minutes on November 18, 2026. That document revealed that “almost all participants” judged additional rate increases would likely be appropriate to drag inflation back to the 2% statutory goal.
The Committee previously delivered a 25-basis-point increase on September 16, 2026—its first rate hike in three years—before pausing in a 10–2 vote on October 28. Governor Lisa Cook and Cleveland Fed President Beth Hammack both dissented in favor of raising rates immediately, marking Cook’s first dissent since joining the Board in 2022.
Governor Christopher Waller escalated the debate on November 10, stating that a 50-basis-point move deserved serious consideration if October core inflation printed at 0.3% month-over-month. Hours later, the U.S. Bureau of Labor Statistics October 2026 CPI Report confirmed core prices climbed exactly 0.3% for the third consecutive month.
“Hiking only 25 basis points would put our credibility at risk, a risk I am not eager to take,” Waller warned. In a November 18 CNBC interview, he doubled down, arguing that without explicit forward guidance signaling a January increase, policymakers must move by 50 basis points in December.
Caption: Federal Reserve policy transcripts and Bureau of Labor Statistics inflation schedules released in Washington, D.C., show broad consensus among FOMC officials for tighter monetary conditions heading into December 2026.
Two structural price shocks dominate internal Federal Reserve discussions right now. First, rapid artificial intelligence data-center construction has driven up electricity demand, specialized hardware prices, and business capital outlays.
Second, geopolitical disruptions tied to the Iran conflict have rattled shipping lanes in the Strait of Hormuz. Waller cited internal Fed research showing tanker insurance and ship-to-ship transfers are adding $20 to $30 per barrel to crude prices, keeping US diesel costs elevated well into 2027.
Federal Regulations and Fed Rate Hike December 2026 Precedents
Under Section 2A of the Federal Reserve Act (12 U.S.C. 225a), the FOMC is legally bound to pursue maximum employment and stable prices. When analyzing Fed rate hike December 2026 precedents, officials point to October’s robust labor report, which showed US employers adding 165,000 jobs above consensus expectations.
Because hiring remains resilient, Governor Cook argued during her November 20 remarks that the current 3.75% to 4.00% policy band is insufficiently restrictive. A November 12, 2026 Federal Reserve working paper reinforced her timing concern, finding that AI capital spending is fueling immediate demand while aggregate productivity gains remain minimal.
Not every policymaker shares Waller’s urgency for a half-point jolt. New York Fed President John Williams remarked on November 17 that current conditions do not require “dramatic action,” while Treasury Secretary Scott Bessent cautioned against tightening directly into an energy supply shock.
Meanwhile, commercial lenders adjust consumer credit products under Truth in Lending Act (TILA) Regulation Z (12 CFR Part 1026), enforced by the Consumer Financial Protection Bureau. Variable-rate credit cards and home equity lines tied to the US Prime Rate automatically reprice within one to two billing cycles after any FOMC adjustment.
Data Breakdown & Comparative Matrix (2025 vs. 2026 Standards)
Market benchmarks have already moved aggressively ahead of the December 9 decision. The table below compares late-2025 borrowing and yield standards against verified November 2026 readings and projected post-December ranges.
| Financial Metric / US Benchmark | Late 2025 Baseline | Current Level (Nov. 2026) | Projected Post-Dec. 9 (25–50 Bps Hike) | Primary US Source |
| Federal Funds Target Range | 3.50%–3.75% (Post-2025 cuts) | 3.75%–4.00% | 4.00%–4.25% or 4.25%–4.50% | Federal Reserve Board |
| US 30-Year Fixed Mortgage | 6.26% (Nov. 2025) | 7.28% (Nov. 19, 2026) | 7.40%–7.65% | Freddie Mac PMMS |
| US 15-Year Fixed Mortgage | 5.54% (Nov. 2025) | 6.66% (Nov. 19, 2026) | 6.75%–7.00% | Freddie Mac PMMS |
| Credit Card APR (Assessed Interest) | ~21.5%–21.9% | 22.36% (24.00% new offers) | 22.61%–22.86% | Federal Reserve / LendingTree |
| 60-Month New Auto Loan APR | ~6.5%–6.8% | 6.99% (7.3% Edmunds avg.) | 7.20%–7.50% | Bankrate / Edmunds |
| 3-Month US Treasury Yield | 3.62% (End-2025) | 4.34% (Nov. 20, 2026) | 4.55%–4.85% | US Treasury / Morningstar |
| 10-Year US Treasury Yield | ~4.2%–4.4% | 4.94%–5.05% (Nov. 19–20) | 5.00%–5.25% | US Treasury Market Data |
Even before Chair Kevin Warsh takes the podium, pricing for a Fed rate hike December 2026 has already sent shockwaves through long-term debt. According to the Freddie Mac Primary Mortgage Market Survey, the average 30-year fixed mortgage jumped 17 basis points in a single week to 7.28% on November 19, sitting more than a full percentage point above last November’s 6.26% average.
Wall Street equities absorbed similar valuation pressure as the 10-year Treasury yield pierced 5.05% on November 19 before settling at 4.94% on November 20. High-multiple technology stocks led the November 20 pullback, sending the Nasdaq Composite down 2.25% to 23,879 and the S&P 500 down 2.02% to 7,175.
Real-World Impact: What This Means for American Households
To measure how a Fed rate hike December 2026 hits everyday family budgets, consider a worked scenario for a dual-income suburban household in Columbus, Ohio, carrying an average US FICO Score 8 near 714. Suppose this household is closing on a $400,000 30-year fixed mortgage, financing a $35,000 60-month vehicle, carrying $10,000 in revolving credit card debt, and holding $25,000 in a taxable money market fund.
At November 2025’s 6.26% mortgage rate, principal and interest on a $400,000 loan cost $2,465 per month. At November 19, 2026’s 7.28% average, that exact payment jumped to $2,737 per month—already adding $272 monthly ($3,264 annually) before December’s vote.
If a hawkish December rate increase and steeper dot plot push 30-year mortgage quotes another 25 basis points to 7.53%, the monthly payment climbs to $2,805. That adds another $68 per month ($816 per year), or $24,563 in extra interest over 30 years compared with locking before the meeting.
On their $35,000 auto loan, a jump from Bankrate’s current 6.99% average to 7.49% following a 50-basis-point shift lifts the monthly note from $693 to $701 ($497 extra over five years). Meanwhile, a 50-basis-point increase pushes their 22.36% credit card APR to 22.86%, adding roughly $50 per year in raw annual interest on a $10,000 balance.
The sole silver lining sits in liquid savings: top money market funds yielding 3.74% to 4.00% and 3-month Treasury bills at 4.34% will pass along higher returns. A 50-basis-point boost adds $125 per year in pre-tax yield on $25,000 in cash, partially offsetting—but failing to erase—the net $962 first-year borrowing hit for active borrowers.
Caption: An American homebuyer reviews a Truth in Lending Loan Estimate document alongside monthly mortgage and credit card statements as US borrowing rates hover near multi-year highs.
Regional and Demographic Breakdown Across the States
The squeeze from a Fed rate hike December 2026 falls unevenly across American demographics and housing markets. First-time homebuyers in high-priced coastal states—including California, New York, Massachusetts, and Washington—face steeper debt-to-income hurdles when 30-year rates breach 7.25%.
Borrowers with subprime or near-prime credit scores absorb the harshest rate spreads. Experian data shows auto loan APRs average 13.52% for subprime new-car buyers and 19.10% for used-car buyers, while credit card offers for lower-tier credit profiles average 27.65%.
Retirees and older savers holding short-term certificates of deposit, Treasury ladders, or FDIC-insured high-yield savings accounts stand to benefit as short-term yields climb toward 4.75%. Readers monitoring federal economic policy shifts, household budgeting updates, and employment trends can also track related consumer briefings at SarkariResultine.com.
Step-by-Step Actionable Checklist: How to Prepare Before the Deadline
With fewer than three weeks remaining before the December 9 decision, consumers and investors can still lock in protections against a Fed rate hike December 2026. Follow these five operational steps before markets reprice after November 25 inflation data:
- Lock Mortgage Rates Under TILA Rules: If you are within 30 to 60 days of closing on a home, request a written rate-lock agreement on your Loan Estimate. Review your statutory rate-lock disclosures under CFPB Regulation Z (12 CFR Part 1026) to confirm lock expiration dates and float-down fees.
- Neutralize Variable Credit Card APRs: Request an APR reduction from your card issuer or shift high-interest balances onto a 0% introductory balance transfer card before the Prime Rate resets higher. Even a 3-to-5 percentage point reduction can save over $1,000 on balances above $7,000.
- Secure Credit Union Auto Pre-Approval: Before visiting a dealership, pull pre-approval quotes from federal credit unions, where super-prime 60-month rates remain below the 6.99% national bank average. Keep credit inquiries within a 14-day window so FICO scoring models count them as a single pull.
- Move Idle Checking Cash Into Short-Duration Yields: Transfer excess cash sitting in traditional checking accounts paying under 0.10% into FDIC-insured high-yield savings accounts, money market funds yielding near 4%, or 3-month Treasury bills via TreasuryDirect.
- Rebalance Equity Duration in 401(k) and IRA Accounts: Review portfolio exposure to speculative, high-multiple AI and growth equities that remain vulnerable if the FOMC signals additional hikes for January and March 2027.
Critical Timeline, Enforcement Dates & What Happens Next
Every major catalyst leading into the Fed rate hike December 2026 vote arrives over a compressed 17-day calendar window. Bond traders will react immediately to each federal release below:
- November 25, 2026 (8:30 a.m. EST): The Bureau of Economic Analysis (BEA) publishes the October 2026 Personal Consumption Expenditures (PCE) Price Index—the Fed’s preferred inflation gauge—alongside the second estimate of Q3 2026 GDP. Fed Governor Michelle Bowman estimated 12-month core PCE could reach 3.3%.
- November 25, 2026 (2:00 p.m. EST): The Federal Reserve releases its regional Beige Book, summarizing on-the-ground wage, pricing, and hiring conditions across all 12 Reserve Bank districts.
- November 28, 2026 (12:00 a.m. EST): The FOMC enters its mandatory pre-meeting communications blackout period, halting public speeches by Fed governors and regional presidents.
- December 8–9, 2026: The FOMC convenes in Washington, D.C., releasing its official rate decision, policy statement, and updated Summary of Economic Projections (SEP) dot plot on Wednesday, December 9, at 2:00 p.m. EST.
- December 9, 2026 (2:30 p.m. EST): Chair Kevin Warsh holds the post-meeting press conference, detailing whether policymakers plan follow-up tightening at the January 26–27, 2027 meeting.
- January 26–27 & March 16–17, 2027: JPMorgan Chase, Bank of America, and Deutsche Bank strategists forecast consecutive quarter-point hikes across these early-2027 meetings, potentially lifting the target band to 4.50%–4.75%.
Official Primary Sources & Verification Links
- Board of Governors of the Federal Reserve System — FOMC Minutes (October 27–28, 2026)
- Federal Reserve — FOMC Official Meeting Calendars (2026–2027)
- U.S. Bureau of Labor Statistics — Consumer Price Index Summary (October 2026)
- U.S. Bureau of Economic Analysis — Official Economic Release Schedule
- Freddie Mac — Primary Mortgage Market Survey (Weekly US Rates)
- Consumer Financial Protection Bureau — 12 CFR Part 1026 (Truth in Lending / Regulation Z)
- Federal Reserve Bank of St. Louis (FRED) — 30-Year Fixed Rate Mortgage Series
Frequently Asked Questions (People Also Ask)
Is a Fed rate hike December 2026 officially guaranteed?
A Fed rate hike December 2026 is not legally final until the FOMC votes on December 9, 2026, at 2:00 p.m. EST. However, CME FedWatch and prediction markets price an 86% to 97% probability of at least a 25-basis-point increase following October’s hawkish FOMC minutes and sticky 0.3% core CPI reading.
Could the Federal Reserve really hike rates by 50 basis points in December?
A 50-basis-point increase remains a minority scenario, carrying roughly 3% to 10% market-implied odds as of late November 2026. Governor Christopher Waller stated a half-point hike should be on the table if policymakers refuse to clearly signal another increase for January 2027, though New York Fed President John Williams pushed back against “dramatic action”.
How quickly will a December Fed rate hike affect my credit card APR?
Variable-rate credit cards track the US Prime Rate, which typically adjusts upward by the exact amount of a Federal Reserve hike within 24 to 48 hours of the announcement. Under CFPB Regulation Z rules, most US cardholders will see the higher APR reflected within one to two monthly billing statements.
Why did 30-year mortgage rates jump to 7.28% before the Fed even met?
Mortgage lenders price 30-year fixed home loans off the 10-year US Treasury yield rather than the overnight federal funds rate. Because bond traders pushed the 10-year yield above 5.0% in anticipation of multiple Fed hikes through early 2027, mortgage rates climbed ahead of the actual December 9 vote.
How do higher Federal Reserve interest rates hurt tech and AI stocks?
Higher interest rates raise the discount rate Wall Street analysts use to calculate the present value of future corporate earnings, disproportionately penalizing high-valuation growth and AI stocks. Rising yields on risk-free 3-month Treasury bills (4.34%) and 10-year notes (near 5.0%) also draw institutional capital away from equities into fixed income.
Leave a Reply