The official rollout of the Citi AAdvantage new card benefits has completely reshaped the landscape for American travelers seeking to maximize their airline rewards in a high-interest-rate environment. Announced on October 27, 2026, this massive overhaul directly impacts millions of US households carrying the Platinum Select and Business World Elite Mastercards. Industry analysts immediately flagged this structural shift as one of the most aggressive loyalty program recalibrations in modern commercial aviation. The comprehensive adjustments fundamentally alter how domestic consumers earn and burn their co-branded airline miles.
With the Federal Reserve holding benchmark rates steady and consumer debt under intense scrutiny, these upgraded reward frameworks represent a calculated shift away from simple mileage accumulation toward premium lifestyle perks. The stakes are undeniably high for everyday Americans, as the introduction of these features arrives alongside a staggering 50% increase in the annual maintenance fee, jumping from $99 to $150. Financial planners are urging middle-class families to rigorously audit their monthly spending habits before their next cardholder anniversary date. Navigating this complex financial terrain requires a forensic understanding of how each new statement credit actively offsets the elevated base carrying costs.
Key Takeaways (Fast Facts)
- Who: American Airlines and Citi targeting US consumer and business credit cardholders.
- What: Implementation of Citi AAdvantage new card benefits including Walmart+ memberships, Global Entry credits, and a $150 annual fee.
- When: Announced October 27, 2026; fee increases take effect January 24, 2027.
- Where: Nationwide across all 50 US states.
- Why: To align with premium travel demand while navigating stringent federal lending environments.
Alt Text: An American Airlines passenger jet reflecting the 2026 rollout of Citi AAdvantage new card benefits for US consumers.
Behind the Official Announcement: Citi AAdvantage New Card Benefits and What Triggered This Shift
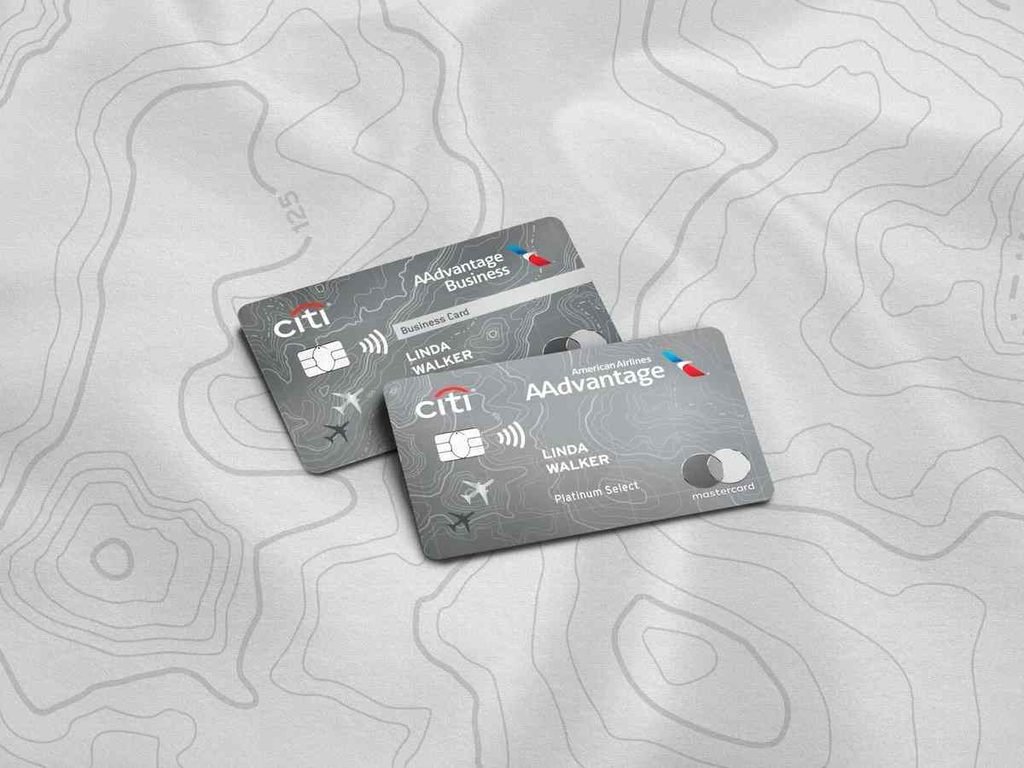
The strategic deployment of the Citi AAdvantage new card benefits comes at a critical juncture for the domestic travel sector and US financial institutions. Wall Street analysts and banking insiders have long anticipated a restructuring of co-branded airline portfolios as lenders face mounting pressure from state usury caps and tightening federal oversight. Airlines can no longer rely exclusively on seat upgrades to drive multi-billion-dollar credit card portfolios. They must now seamlessly integrate their loyalty currency into the daily retail habits of the American consumer base.
By fundamentally altering the core value proposition, Citi’s aggressive pivot forces cardholders to evaluate whether their organic spending aligns with the newly added lifestyle credits. The issuer systematically replaced the legacy 25% inflight food and beverage discount with a capped $100 annual inflight statement credit. This bold maneuver changes the underlying mathematics for frequent domestic flyers who routinely purchase Wi-Fi or premium snacks at 35,000 feet. Capping the discount establishes a hard ceiling on annual consumer savings while boosting the airline’s ancillary revenue metrics.
Furthermore, the inclusion of a complimentary Walmart+ membership—valued at roughly $98 annually—signals a deliberate effort to capture household spending far beyond the physical airport terminal. The ultimate success of this program refresh will largely depend on whether working-class Americans can organically absorb these new merchant partnerships without altering their standard monthly budget. Forging alliances with massive big-box retailers demonstrates a clear strategy to position the co-branded card at the front of the consumer’s digital wallet. Cardholders must remember that this specific perk requires manual activation and is subject to automated renewal cycles.
For independent contractors relying on 1099 income, the business variant introduces a self-selected 2x multiplier for US shipping or domestic advertising services. This distinct separation between consumer and commercial utility reflects the broader macroeconomic trend of tailoring financial products to specialized tax brackets and enterprise scales. Small business owners must now actively manage their quarterly spending categories to extract maximum value from their corporate overhead. Furthermore, commercial users gain access to a 25% discount on Melio software subscriptions, driving domestic B2B payment efficiency.
Federal and Regulatory Precedents Influencing Citi AAdvantage New Card Benefits
Behind the scenes, the structural design of the Citi AAdvantage new card benefits is heavily influenced by the evolving regulatory posture of the Consumer Financial Protection Bureau (CFPB) and the Federal Trade Commission (FTC). With federal regulators cracking down on junk fees and enforcing stricter Truth in Lending Act (TILA Regulation Z) disclosures, major issuers must ensure that new perks transparently offset higher annual carrying costs. Washington lawmakers continue to apply intense scrutiny to credit card reward programs that mask predatory lending practices beneath complex point valuations. Transparency regarding exactly how and when consumers can redeem these advertised credits remains a top enforcement priority.
The $150 annual fee places these financial products under a brighter spotlight regarding tangible consumer value delivery. When banking institutions raise baseline holding costs, federal watchdogs often monitor customer attrition rates to ensure that the advertised rewards remain realistically attainable for the average American earning standard W-2 wages. Regulators demand that banks clearly articulate the difference between actual monetary savings and highly conditional statement credits. Providing unambiguous terms protects working families from absorbing fees for luxury services they never physically utilize.
Additionally, the travel protections bundled within this financial package—such as trip delay and lost baggage coverage—must legally comply with strict state-by-state insurance department regulations. These robust domestic consumer safety nets differentiate regulated American credit markets from less standardized international financial sectors. By offering primary car rental coverage and substantial trip cancellation limits, the bank legally binds itself to strict domestic underwriting statutes. Claiming these benefits requires meticulously documented proof of loss, ensuring strict adherence to US fraud prevention laws.
Key Data & Comparative Breakdown (At a Glance)
To truly understand the direct financial impact of the Citi AAdvantage new card benefits, consumers must ruthlessly compare the legacy rewards structure against the upcoming 2027 framework. The detailed comparison matrix below isolates the exact metric shifts facing current Platinum Select cardholders residing in the United States. Evaluating these critical data points allows households to properly forecast their annual airline loyalty return on investment. Adjusting your budget based on these confirmed metrics is the only reliable way to outpace banking inflation.
| Feature / Benefit Category | Legacy Platinum Select Terms (Pre-2026) | New 2026/2027 Policy Updates |
| Annual Maintenance Fee | $99 (Waived first 12 months) | $150 (Effective January 24, 2027) |
| AAdvantage Hotel & Car | Standard 1x Base Earning | Accelerated 3x Mileage Earning |
| Inflight Purchase Perk | 25% Uncapped Statement Discount | Capped $100 Annual Statement Credit |
| TSA PreCheck/Global Entry | Not Included in Base Card | Up to $120 Credit Every 4 Years |
| US Retail Partnerships | None Available | Free Walmart+ Membership ($98 Value) |
| Routine Commuter Perks | Standard 1x Base Earning | 2x on Rides, Rails, and EV Charging |
This matrix illustrates how the refreshed portfolio deliberately pivots away from unlimited percentage-based discounts toward heavily capped, flat-rate statement credits. Independent financial advisors frequently warn that flat-rate credits require users to front the cash first, thereby relying on the issuer’s automated ACH transfer rails to process reimbursements within a standard 30-day billing cycle. This subtle mechanical shift transfers immediate liquidity pressure directly onto the consumer. Households operating on tight monthly margins must ensure they possess the cash flow to absorb the initial purchase before the credit eventually clears.
Maximizing the Citi AAdvantage new card benefits now demands a highly active administrative management style, forcing consumers to physically link their accounts to third-party services like Walmart+ and the Fox One streaming platform. If a cardholder fails to trigger these specific merchant codes, the increased $150 annual fee will rapidly erode any baseline mileage gains earned at the local supermarket or gas pump. Passive consumers will ultimately subsidize the rich rewards extracted by highly engaged power users. Remaining complacent with your digital wallet settings is mathematically equivalent to handing the bank a yearly cash donation.
Real-World Impact: What This Means for Everyday Americans
The tangible pocketbook impact of the Citi AAdvantage new card benefits cannot be overstated for families actively managing their FICO Score 8 profiles. Any spontaneous decision to upgrade, downgrade, or prematurely cancel a credit line directly influences your revolving credit utilization ratio and the average age of your accounts. These precise metrics remain the absolute bedrock of modern domestic credit scoring monitored by Experian, TransUnion, and Equifax. Maintaining a pristine credit file dictates your future borrowing power for American mortgages and standard auto loans.
For everyday Americans, transitioning to this upgraded framework means rigorously reassessing daily commuting routes and recurring streaming subscriptions. Because the 2x multiplier on gas stations has been modernized to legally include certified EV charging stations, coastal and urban motorists who have transitioned to electric vehicles finally gain reward parity with traditional combustion engine drivers. With modern EVs routinely weighing over 4,000 lbs and pushing 70 mph on interstate commutes, the expanded charging rewards directly benefit heavy-mileage American motorists. Capitalizing on these transit categories ensures that daily unavoidable expenses actively fund your next domestic vacation.
However, navigating the complex web of the Citi AAdvantage new card benefits requires an ironclad approach to discretionary spending to prevent debt accumulation at variable APRs reaching up to 29.74%. Carrying any revolving balance on this specific travel card will instantly and mathematically negate the value of the free checked bags and the $150 flight discount threshold. Accruing double-digit interest charges remains the fastest way to decimate the intrinsic value of earned frequent flyer miles. If you cannot pay the statement balance in full every month, reward-focused credit cards become an active financial liability.
For comprehensive updates on consumer rights, career opportunities, and economic policy, visit SarkariResultine.com.
Ultimately, this financial product is meticulously tailored for the upper-middle-class traveler who organically utilizes TSA PreCheck protocols and heavily relies on domestic grocery delivery logistics. Consumers must rigorously track their localized monthly expenditures against these new structural caps to ensure they remain financially ahead of the impending $150 base fee. Failing to execute a personalized break-even analysis will leave cardholders paying a premium for luxury benefits they never physically activate. Financial discipline is the only tool that prevents issuers from profiting off your unused perks.
Critical Timeline & What Happens Next
The rollout phase for the Citi AAdvantage new card benefits is designed around a staggered domestic timeline, giving current account holders a brief but vital window to strategize. While the official press release was globally dispatched on October 27, 2026, the harsh reality of the $150 annual fee will not strike existing American accounts until January 24, 2027. This specific operational delay prevents mass consumer panic during the highly lucrative Q4 holiday shopping season. Utilizing this buffer period to restructure your wallet is a mandatory step for proactive household budgeting.
This statutory grace period allows US taxpayers to evaluate their upcoming holiday spending and accurately forecast whether they can realistically hit the $20,000 annual spend required to unlock the newly elevated $150 flight discount. Proactive consumers should immediately log into their secure banking portals to manually opt-in to the retail features embedded within the upgraded contract. Activating these external partnerships often requires reading secondary sets of dense merchant terms and conditions. Missing a simple registration step nullifies the statement credits you are effectively paying for via the higher annual fee.
Failure to adjust your digital wallet settings before the strict January 2027 deadline means absorbing the higher holding costs without harvesting the associated Citi AAdvantage new card benefits. Financial planners strongly advise setting smartphone calendar alerts exactly 30 days prior to your specific anniversary date to conduct a final, objective cost-benefit analysis. A timely downgrade strategy can save households over a hundred dollars in unrecoverable bank fees. Taking swift, decisive action always beats passive corporate loyalty when dealing with massive US banking conglomerates.
Official Verification & Primary US Resources
To ensure complete financial transparency regarding the Citi AAdvantage new card benefits, consumers are strongly encouraged to cross-reference our reporting with official federal databases and corporate disclosures. Blindly trusting third-party credit card marketing often leads to unforeseen financial penalties and damaged domestic credit scores. The following primary sources provide strict statutory guidance on US credit card regulations, verified consumer rights, and official corporate issuer terms. Consulting these portals guarantees you are operating with certified government data.
- Consumer Financial Protection Bureau (CFPB): Review official federal guidelines on credit card fee transparency, statutory late fee caps, and consumer complaint procedures regarding deceptive rewards programs. Visit consumerfinance.gov.
- Federal Trade Commission (FTC): Track active enforcement actions and explore your legal consumer rights related to deceptive financial marketing and Truth in Lending Act (TILA) disclosures. Visit ftc.gov.
- US Securities and Exchange Commission (SEC): Review Citigroup Inc.’s official 8-K filings, quarterly earnings calls, and corporate disclosures detailing the macroeconomic rollout of the 2026 portfolio refresh. Visit sec.gov.
Frequently Asked Questions (Fast Answers)
When do the Citi AAdvantage new card benefits actually take effect for existing customers?The updated structural perks associated with the Citi AAdvantage new card benefits were publicly announced on October 27, 2026. However, the increased $150 annual fee officially hits domestic billing statements starting January 24, 2027, granting current cardholders a brief grace period to adjust their financial strategies.
Are the Citi AAdvantage new card benefits genuinely worth the increased $150 annual fee?Yes, provided that the targeted cardholder organically utilizes the Citi AAdvantage new card benefits like the complimentary Walmart+ membership and the TSA PreCheck reimbursement. If you strictly fly American Airlines once a year and completely ignore the new lifestyle credits, the mathematical break-even point no longer works in your favor.
How do the Citi AAdvantage new card benefits impact registered US business owners?The commercial variant introduces a highly flexible, self-selected 2x multiplier for US shipping or domestic advertising services, helping LLCs and sole proprietors optimize their tax-deductible overhead. Furthermore, registered business owners gain a 25% structural discount on Melio software subscriptions to aggressively streamline their domestic US vendor payments.
Do the Citi AAdvantage new card benefits still include the standard free checked bags?Yes, the foundational consumer perk of a free first checked bag on domestic American Airlines flights remains completely intact under the new contract. This specific aviation feature alone can save a traveling family of four up to $280 on a standard round-trip domestic vacation, easily offsetting the base annual fee.
Can I legally downgrade my account to avoid the fee associated with the Citi AAdvantage new card benefits? Yes, American consumers possess the legal right to request a product change to a no-annual-fee alternative, such as the standard AAdvantage MileUp card. Executing a formal product change preserves your domestic credit history, maintains your revolving credit limits, and effectively prevents a negative hit to your FICO Score 8.